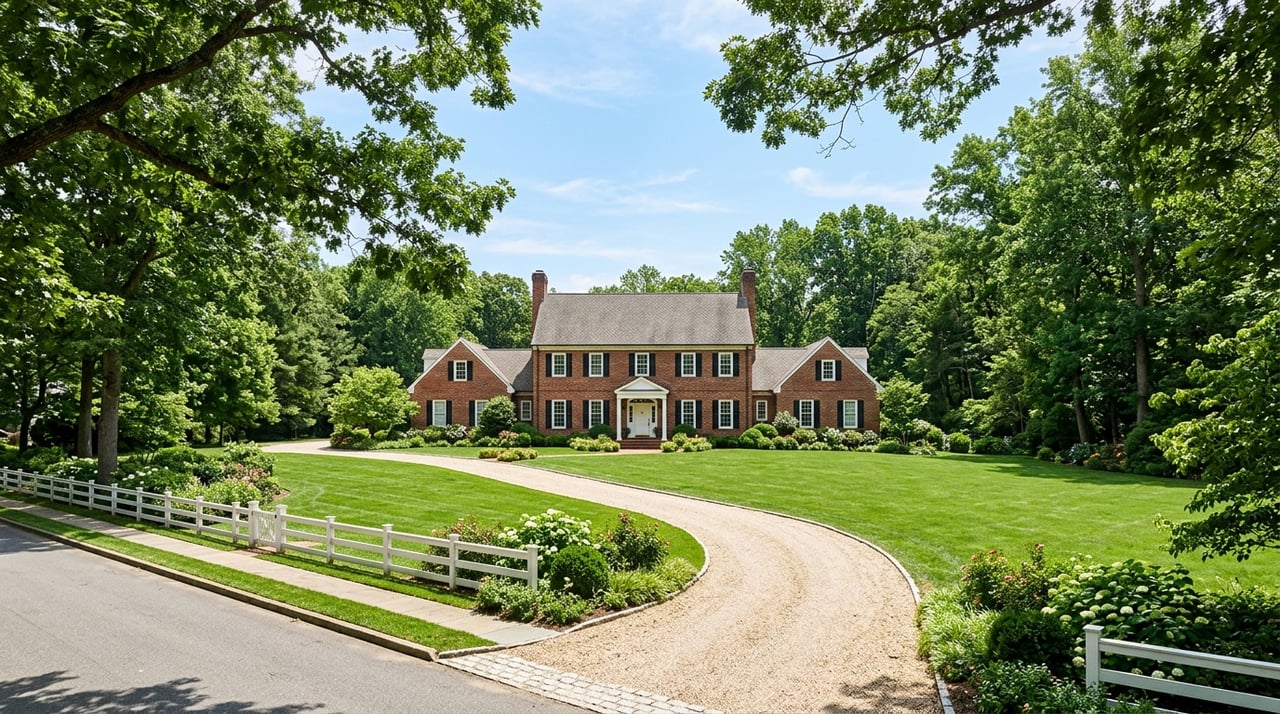
Homeowners insurance policies cover six standard protection areas: Dwelling (Coverage A), Other Structures (Coverage B), Personal Property (Coverage C), Loss of Use (Coverage D), Personal Liability (Coverage E), and Medical Payments (Coverage F). For luxury estates in McLean VA, high-value HO-5 open-peril policies replace standard HO-3 contracts to cover full custom reconstruction costs.
Purchasing a luxury residence or preparing an estate acquisition in McLean or Great Falls VA? Explore active listings in McLean VA homes for sale, or review our relocation and neighborhood breakdown in living in McLean VA before finalizing your closing timeline.
Policy Coverage Pillar | Policy Section | Standard HO-3 Baseline | High-Value HO-5 Estate Profile | Primary Protection & Risk Note |
|---|---|---|---|---|
Coverage A: Dwelling | Section I (Property) | Basic replacement or market cap | Guaranteed custom reconstruction cost | Insures physical structure, roof, walls, and attached garages |
Coverage B: Other Structures | Section I (Property) | 10% cap of Coverage A limit | Expanded custom structural allocations | Covers detached guest houses, pool cabanas, fences, and gates |
Coverage C: Personal Property | Section I (Property) | Named perils; Actual Cash Value | Open peril; Full Replacement Cost + riders | Protects furniture, electronics, and scheduled fine art or jewelry |
Coverage D: Loss of Use | Section I (Property) | 20% to 30% of Coverage A cap | Uncapped or extended 24-month limit | Funds comparable temporary housing during covered structural repairs |
Coverage E: Personal Liability | Section II (Liability) | $100,000 to $300,000 baseline | $1,000,000 to $5,000,000 + umbrella | Covers legal defense and court judgments for guest injuries |
Coverage F: Medical Payments | Section II (Liability) | $1,000 to $5,000 per person | $10,000 to $25,000 per person | Pays minor guest medical bills regardless of legal fault |
The Six Standard Homeowners Insurance Coverages Explained (Section I & Section II)
Understanding what a homeowners insurance policy covers is essential for both first-time homebuyers and luxury estate owners across Northern Virginia. Standard residential policies divide protection into Section I property coverages and Section II liability coverages across six core policy pillars labeled Coverage A through Coverage F. Coverage A (Dwelling) protects the physical structure of the home, including walls, roofing, foundations, and attached garages against sudden perils like fire, windstorms, and hail. Coverage B (Other Structures) insures detached assets on the parcel such as perimeter masonry walls, gates, pools, and guest houses, typically capped at 10 percent of Coverage A unless expanded by endorsement.
Coverage C (Personal Property) reimburses damaged or stolen interior belongings, including furniture, electronics, and clothing. Choosing full Replacement Cost coverage over Actual Cash Value ensures payouts reflect modern retail prices without depreciation deductions, while scheduled personal property riders protect fine art, jewelry, and wine collections above standard sub-limits. Coverage D (Loss of Use or Additional Living Expenses) funds comparable temporary residential leasing and living costs if a covered loss renders the residence uninhabitable during structural repairs. Section II includes Coverage E (Personal Liability), which defends against bodily injury or property damage lawsuits up to $100,000 on standard policies or $1,000,000 to $5,000,000 on high-value policies, and Coverage F (Medical Payments), which covers minor guest injuries without litigation.
- Virginia State Corporation Commission Bureau of Insurance: 1300 East Main Street, Richmond, VA 23219, phone (804) 371-9741, regulating Virginia residential property insurance forms and consumer guidelines.
- National Flood Insurance Program (NFIP) / FEMA: Administering federal flood zone maps and separate flood insurance policies for Fairfax County parcels.
- Fairfax County Land Development Services: 12055 Government Center Parkway, Fairfax, VA 22035, phone (703) 222-0801, providing residential floodplain and building code records.
HO-3 vs. HO-5 Policies, Major Exclusions, and High-Value Estate Protection
Selecting the right contract form determines how broadly perils are insured. A standard HO-3 Special Form policy covers the physical dwelling on an open-peril basis (covering all hazards except listed exclusions) but restricts personal belongings to named perils only. Conversely, an HO-5 Comprehensive Form policy insures both the dwelling and personal contents on an unrestricted open-peril basis, making it the preferred standard for custom luxury residences in McLean and Great Falls. Furthermore, insuring Coverage A based on full architectural reconstruction cost rather than real estate market value prevents severe under-insurance when custom millwork and imported stone must be replicated.
Homeowners must also account for major policy exclusions that require separate contracts or riders. Standard policies exclude overland flood inundation (which requires a National Flood Insurance Program or private flood policy), earth movement and earthquakes, sewer and sump pump backups, and gradual wear or maintenance neglect. Coordinating policy binding prior to closing guarantees seamless lender compliance and asset security across Fairfax County.
To optimize annual premiums in 2026, property owners should bundle central station fire alarms, automated water leak shutoff valves, and backup generators to earn insurer mitigation credits while maintaining strong credit-based insurance scores. Partnering with Susan Wisely and experienced private client insurance advisors ensures every architectural feature and detached structure is properly underwritten from the day of closing.
For further guidance on acquiring and maintaining premier Northern Virginia residences, review our guides on moving to McLean VA, the path to owning an ultra-luxury home in McLean VA, and Great Falls VA real estate.
Related Northern Virginia Homeownership & Estate Guides
- Living in McLean VA: Neighborhood & Lifestyle Guide
- Everything You Need to Know About Moving to McLean VA
- The Path to Owning an Ultra-Luxury Home in McLean VA
- Great Falls VA Real Estate & Acreage Estates
- Top Things to Do in McLean VA
Frequently Asked Questions
What are the 6 parts of a standard homeowners insurance policy?
A standard homeowners insurance policy includes six core coverages: Coverage A (Dwelling), Coverage B (Other Structures), Coverage C (Personal Property), Coverage D (Loss of Use / Additional Living Expenses), Coverage E (Personal Liability), and Coverage F (Medical Payments to Others).
What is the difference between HO-3 and HO-5 homeowners insurance?
An HO-3 policy covers the physical house on an open-peril basis but insures personal belongings only against named perils listed in the policy. An HO-5 policy provides broader open-peril protection for both the physical structure and personal property, making it the preferred standard for high-value homes.
What does homeowners insurance typically not cover?
Standard homeowners insurance policies exclude overland flooding, earthquakes and earth movement, sewer or sump pump backups (unless added by endorsement), and damage caused by gradual wear, mold, or routine maintenance neglect.
Should Dwelling Coverage A match a home's real estate market value?
No. Coverage A should be calculated based on full architectural reconstruction cost (labor and building materials required to rebuild the structure), not real estate market value, which includes land value that cannot be destroyed by fire or wind.
What is the difference between Actual Cash Value and Replacement Cost?
Actual Cash Value (ACV) reimburses the depreciated value of damaged belongings based on their age and condition. Replacement Cost coverage pays the full amount needed to purchase brand-new comparable items at current retail prices without deduction for depreciation.
Susan Wisely, Principal & Founder | Choose Wisely Group at Compass
Susan Wisely is a trusted luxury real estate advisor serving McLean, Great Falls, Vienna, and Reston in Northern Virginia. With decades of experience guiding high-net-worth buyers and sellers through complex acquisitions, Susan coordinates with private client underwriting specialists to ensure custom estates, detached structures, and fine collections are fully protected at closing. Connect directly with Susan Wisely at Choose Wisely Group to plan your Northern Virginia home purchase.
Ready to navigate your next Northern Virginia real estate acquisition with confidence? Schedule a private real estate consultation with Susan Wisely